
johnnie0105869
About johnnie0105869
Random Housing Tip
 There is a version of the housing market story that gets told over and over, and it goes like this: prices are high, rates are high, nothing is affordable, and the only people buying are the ones with cash. That version is not wrong, exactly. It is just incomplete.
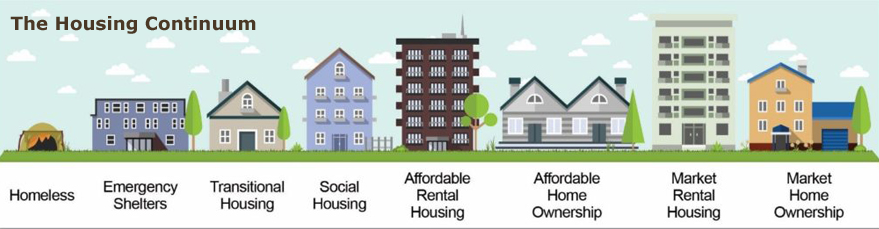 The arithmetic here is brutal and worth understanding clearly. A buyer who financed a $400,000 home at three percent in 2021 pays roughly $1,686 per month on principal and interest. That same loan at a seven percent rate costs $2,661. Those numbers explain why the market froze rather than crashed when rates moved higher. Volume collapsed. Prices mostly did not.
Affordability, by the standard measure of what share of median household income goes toward the monthly payment on a median-priced home, is near its worst level since the early 1980s. That is a real problem, and it is not going away quickly. That measure being at a historical extreme does not automatically produce a correction. What it means, practically, is that the buyer who can close confidently has more leverage than the headline numbers suggest.
 Shop at least three lenders before you commit to one. A quarter-point difference in your interest rate adds up to around twenty thousand dollars over a thirty-year loan on a four hundred thousand dollar mortgage. Lender fees vary too. Do not compare rate quotes without also comparing origination fees, points, and closing costs.
 The appraisal is the lender’s check, not yours. A low appraisal means the buyer has to make up the gap in cash, renegotiate, or cancel. Ask your agent what the local pattern looks like before you structure an offer without an appraisal contingency.
Budget two to four percent of the purchase price for closing costs, on top of your down payment. First-time buyers routinely underestimate this number. Ask your lender for a Loan Estimate with a realistic purchase price so the numbers reflect what you are actually going to face.

Buyers who take the time to prepare before they start looking tend to find that opportunities exist even when conditions look difficult on paper. Current property listings and market tools at real estate listings and data are worth bookmarking before you make any major moves.
No listing found.